Analytics and Reporting for Credit Unions
Most credit unions can tell you how many people visited the auto loan page. Far fewer can tell you how many of them applied, which channel sent them, or what each application cost.
Do you know what your marketing actually produced last quarter?
Talk to Our Analytics Team
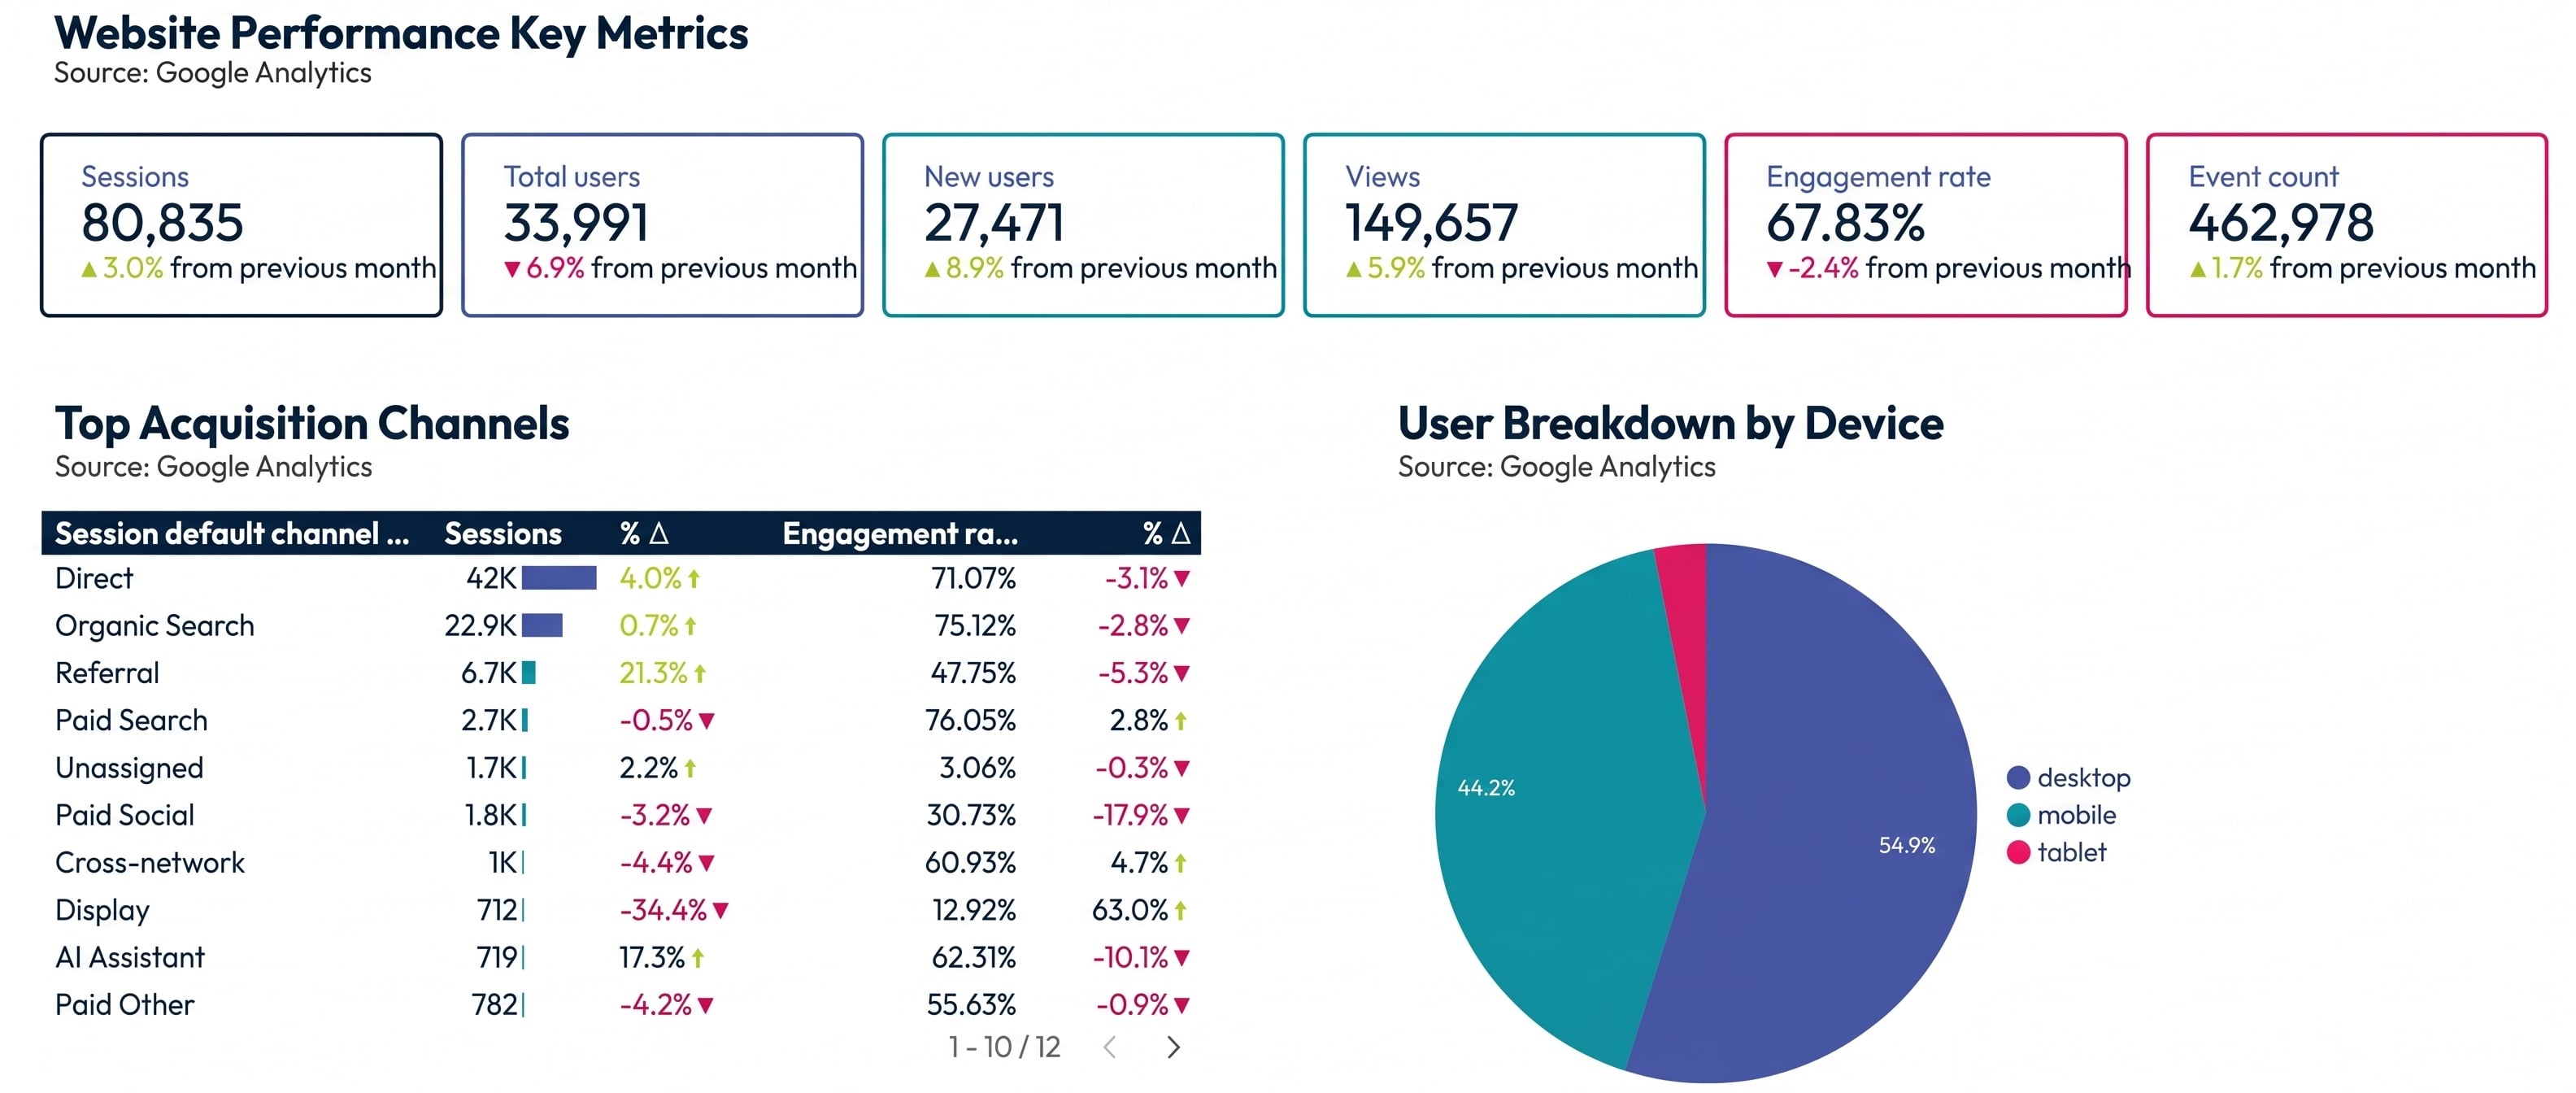
What Should Credit Union Analytics Actually Measure?
Applications, not just clicks.
Impressions, clicks, and sessions tell you people showed up. They don't tell you whether anyone applied for a loan or opened an account, and those are the numbers your board asks about.
Useful credit union reporting answers questions like these:
-
Which channels are producing completed applications?
-
What is our cost per application by channel, campaign, and product?
-
Which products are getting the strongest response?
-
Are people reaching our digital applications, and are they finishing them?
-
Is our tracking working across our website and our third-party platforms?
-
Where the platform allows it, can we tie marketing to funded loans or opened accounts?
Depending on your goals, we may also look at member acquisition cost, share of wallet, or the hours your team gets back once reporting runs on its own.
Is GA4 enough on its own?
GA4 is the right foundation, but out of the box it measures pageviews and sessions. It doesn't know what an application is, and it loses the trail when a member crosses into your LOS. It has to be configured around your conversions, your platforms, and your consent requirements before the numbers mean much.
The Analytics Challenge for Credit Unions

The Handoff
Your most valuable conversions happen on platforms you don't own. MeridianLink, Origence, Encompass, Clutch, and MortgageBot each handle tracking differently. Some allow tags on every step. Some allow almost nothing. There is rarely a one-size-fits-all setup, and a template from another industry won't account for it.

The Compliance Dimension
Tracking member behavior on a financial site comes with obligations. Consent banners, privacy rules, and what can and can't pass to ad platforms all affect your data. Set up wrong, a consent banner can quietly wipe out a large share of your reporting. Set up right, you stay compliant and keep numbers you can use.

The Advantage You Already Have:
Credit unions have something most advertisers don't: a defined membership, a focused product set, and an LOS that already knows who applied. That makes it possible to connect marketing to real outcomes in a way an online-only lender with a dozen funnels can't easily match.
You don't need more data. You need data your team can trust.

Why Credit Unions Trust Geear With Their Data
Here's what's different about working with Geear:
Credit union expertise, not a generic playbook. We've partnered with over 120 credit unions and banks. We know the loan platforms, the compliance questions, and the reports your leadership expects to see.
We've done the LOS work before. Getting tracking through MeridianLink, Origence, Encompass, Clutch, or MortgageBot is specific, technical work. Our team has worked through these integrations before, so we start with what we already know works on your platform.
No contracts. If you're not getting value, you walk away. We earn your business month to month.
SOC 2 Type II certified. Analytics work means access to your website, your ad accounts, and data about member behavior. We hold ourselves to the same security standards your members expect from you, which makes the conversation with your compliance team a lot shorter.
Named practitioners, not anonymous account managers. You'll know who is working on your account, what they've done in credit union marketing, and how to reach them directly.
Ready to See What Your Marketing Is Producing?
Talk to our team about what your current setup captures, what it misses, and how far it reaches into your loan platforms. You'll come away knowing which numbers you can trust and what it would take to fix the rest.
No obligation. No pressure. No contract if you decide to move forward.
)-1.png)

Ready for marketing that actually delivers?
Let's build something measurable together.
 Talk to the Team